What this guidebook covers
Since 2021, payments of €1,000 or more cannot be made in cash when one party is a business. The AEAT (Spanish Tax Agency) fines both the payer and the receiver 25% of the amount: a €3,000 cash deposit means a €750 fine for each. If the dealer is an obliged entity under the Anti-Money Laundering Act (Law 10/2010), very serious infringements start at €150,000.
This guidebook covers 5 cash and anti-money laundering standards, with 14 checkpoints: the cash limit, customer identification, suspicious transactions reported to SEPBLAC, the manual and training, and preparation for the EU AML Regulation that applies from 10 July 2027. The guidebook PDF is in Spanish.
The 5 cash and anti-money laundering standards
| Code | Standard | Ideal fix time |
|---|---|---|
| BLA-01 | Cash limit | Immediate |
| BLA-02 | Customer identification | 72 hours |
| BLA-03 | Suspicious transactions | 24 hours |
| BLA-04 | Manual and training | 30 days |
| BLA-05 | AMLR 2027 preparation | 30 days |
How to run a Spanish cash payments and anti-money laundering audit, step by step
- Confirm what applies. The cash limit always applies. Law 10/2010 only applies to dealers in the cases set out in its article 38, for example cash from non-residents: confirm whether you are an obliged entity.
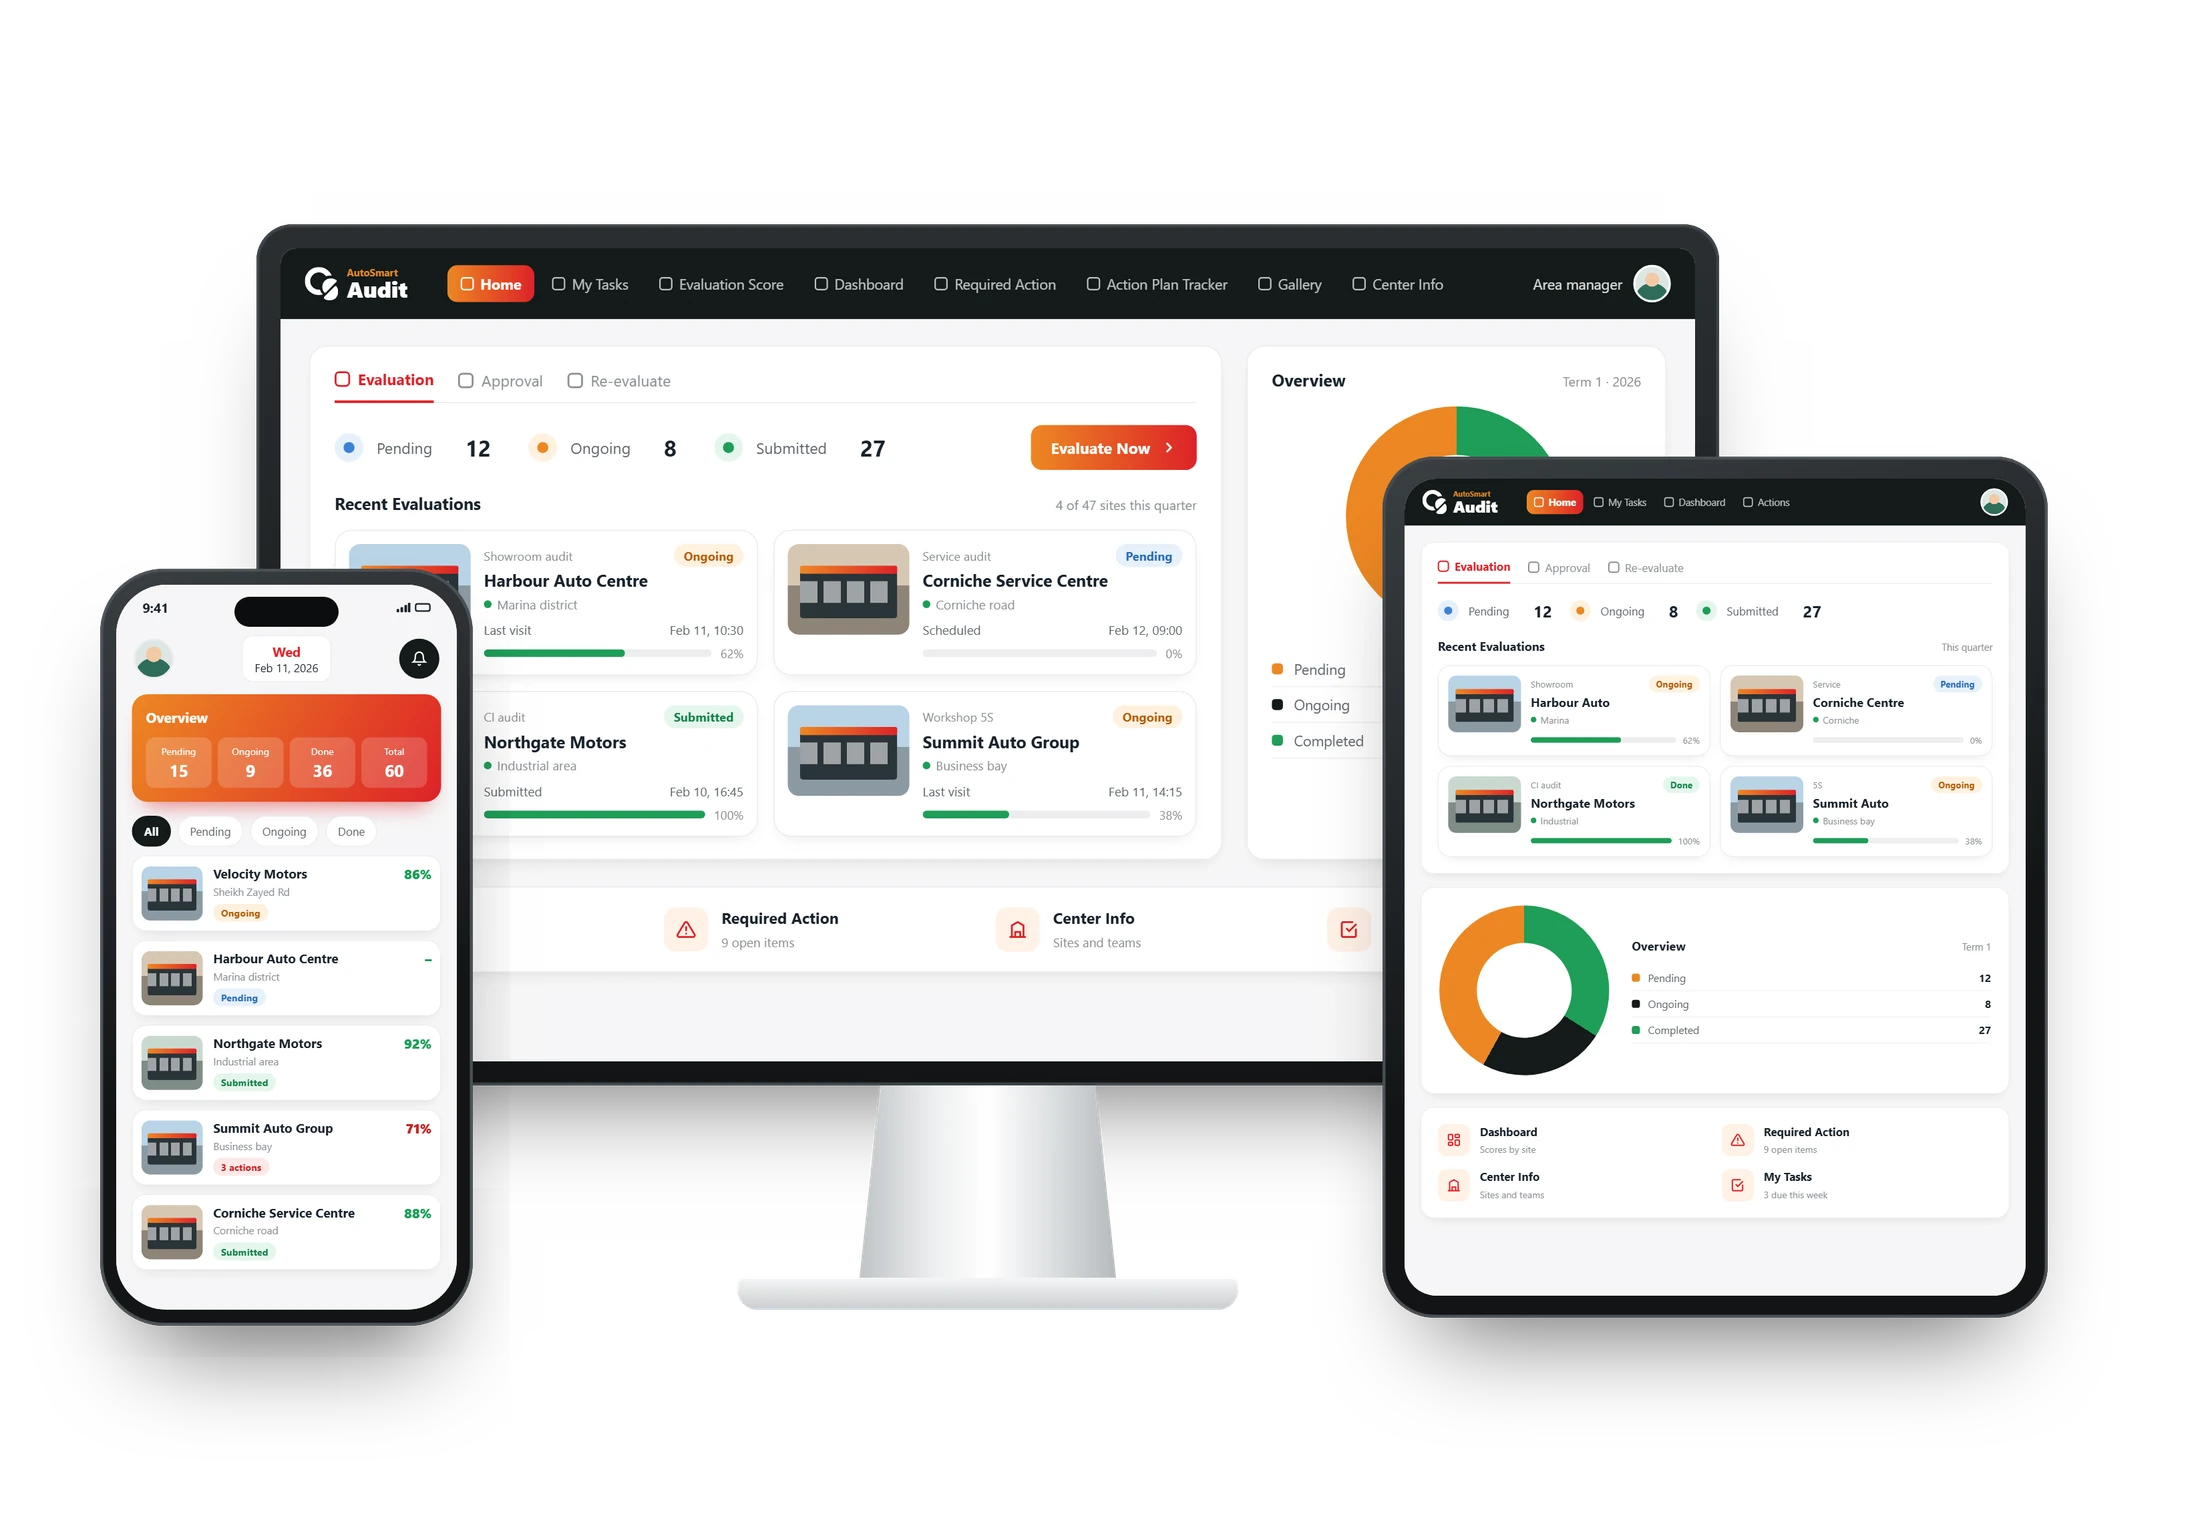
- Walk the site, standard by standard. Score each of the 14 checkpoints Pass, Fail or N/A. N/A only where the standard rules it out, with the reason recorded. Review 3 months of cash records for payments of €1,000 or more and split payments, check 10 deal files for ID and source of funds, and ask 3 salespeople what they do with a suspicious deal.
- Capture the evidence. A pass counts only with proof captured at the time of the audit: cash counts and receipts, deal files with customer ID, the internal reporting log, the AML manual and training records, and the 2027 plan.
- Give every fail an owner and a fix time. Record what you saw and who owns the fix. Each standard carries an ideal fix time, from immediate to 30 days, counted from audit submission (see the table above).
- Fix it, then prove it. The site fixes the cause and uploads proof of closure; the auditor checks the proof before closing the finding.
- Re-check at the next audit. Confirm closed findings stay closed, and look for the same fail at your other sites so one gap doesn't repeat across the network.
Who this guidebook is for
- Management: answers with its own assets
- Cashiers and sales staff: know when to say no
- Auditors: review cash counts and deal files
A reference document, not legal advice. Fines and rules change: check the current text with the regulator or your legal adviser before acting.