What this guidebook covers
Showrooms arrange consumer loans and leases. Faulty information can trigger the free credit sanction (SKD), where the customer repays only the capital, without interest or fees, and UOKiK can also fine up to 10% of turnover. In the guidebook's example, about PLN 25,000 of interest and fees on a PLN 100,000 loan could be lost. The new EU Consumer Credit Directive (CCD2) must be implemented by 20 November 2026.
This guidebook covers 5 standards for the F&I department, with 11 checkpoints: authority to act as a credit intermediary, information before the contract, credit advertising, insurance and add-ons, and readiness for CCD2. The guidebook PDF is in Polish.
The 5 consumer credit standards
| Code | Standard | Ideal fix time |
|---|---|---|
| KRE-01 | Authority to act as credit intermediary | 7 days |
| KRE-02 | Information before the contract | Immediate |
| KRE-03 | Credit advertising | 72 hours |
| KRE-04 | Insurance and add-ons | 72 hours |
| KRE-05 | Ready for CCD2 | 30 days |
How to run a Polish consumer credit audit, step by step
- Confirm what applies. List every lender the showroom offers credit for and check there is an intermediary agreement with each; consumer leasing and long-term rental may fall under other rules.
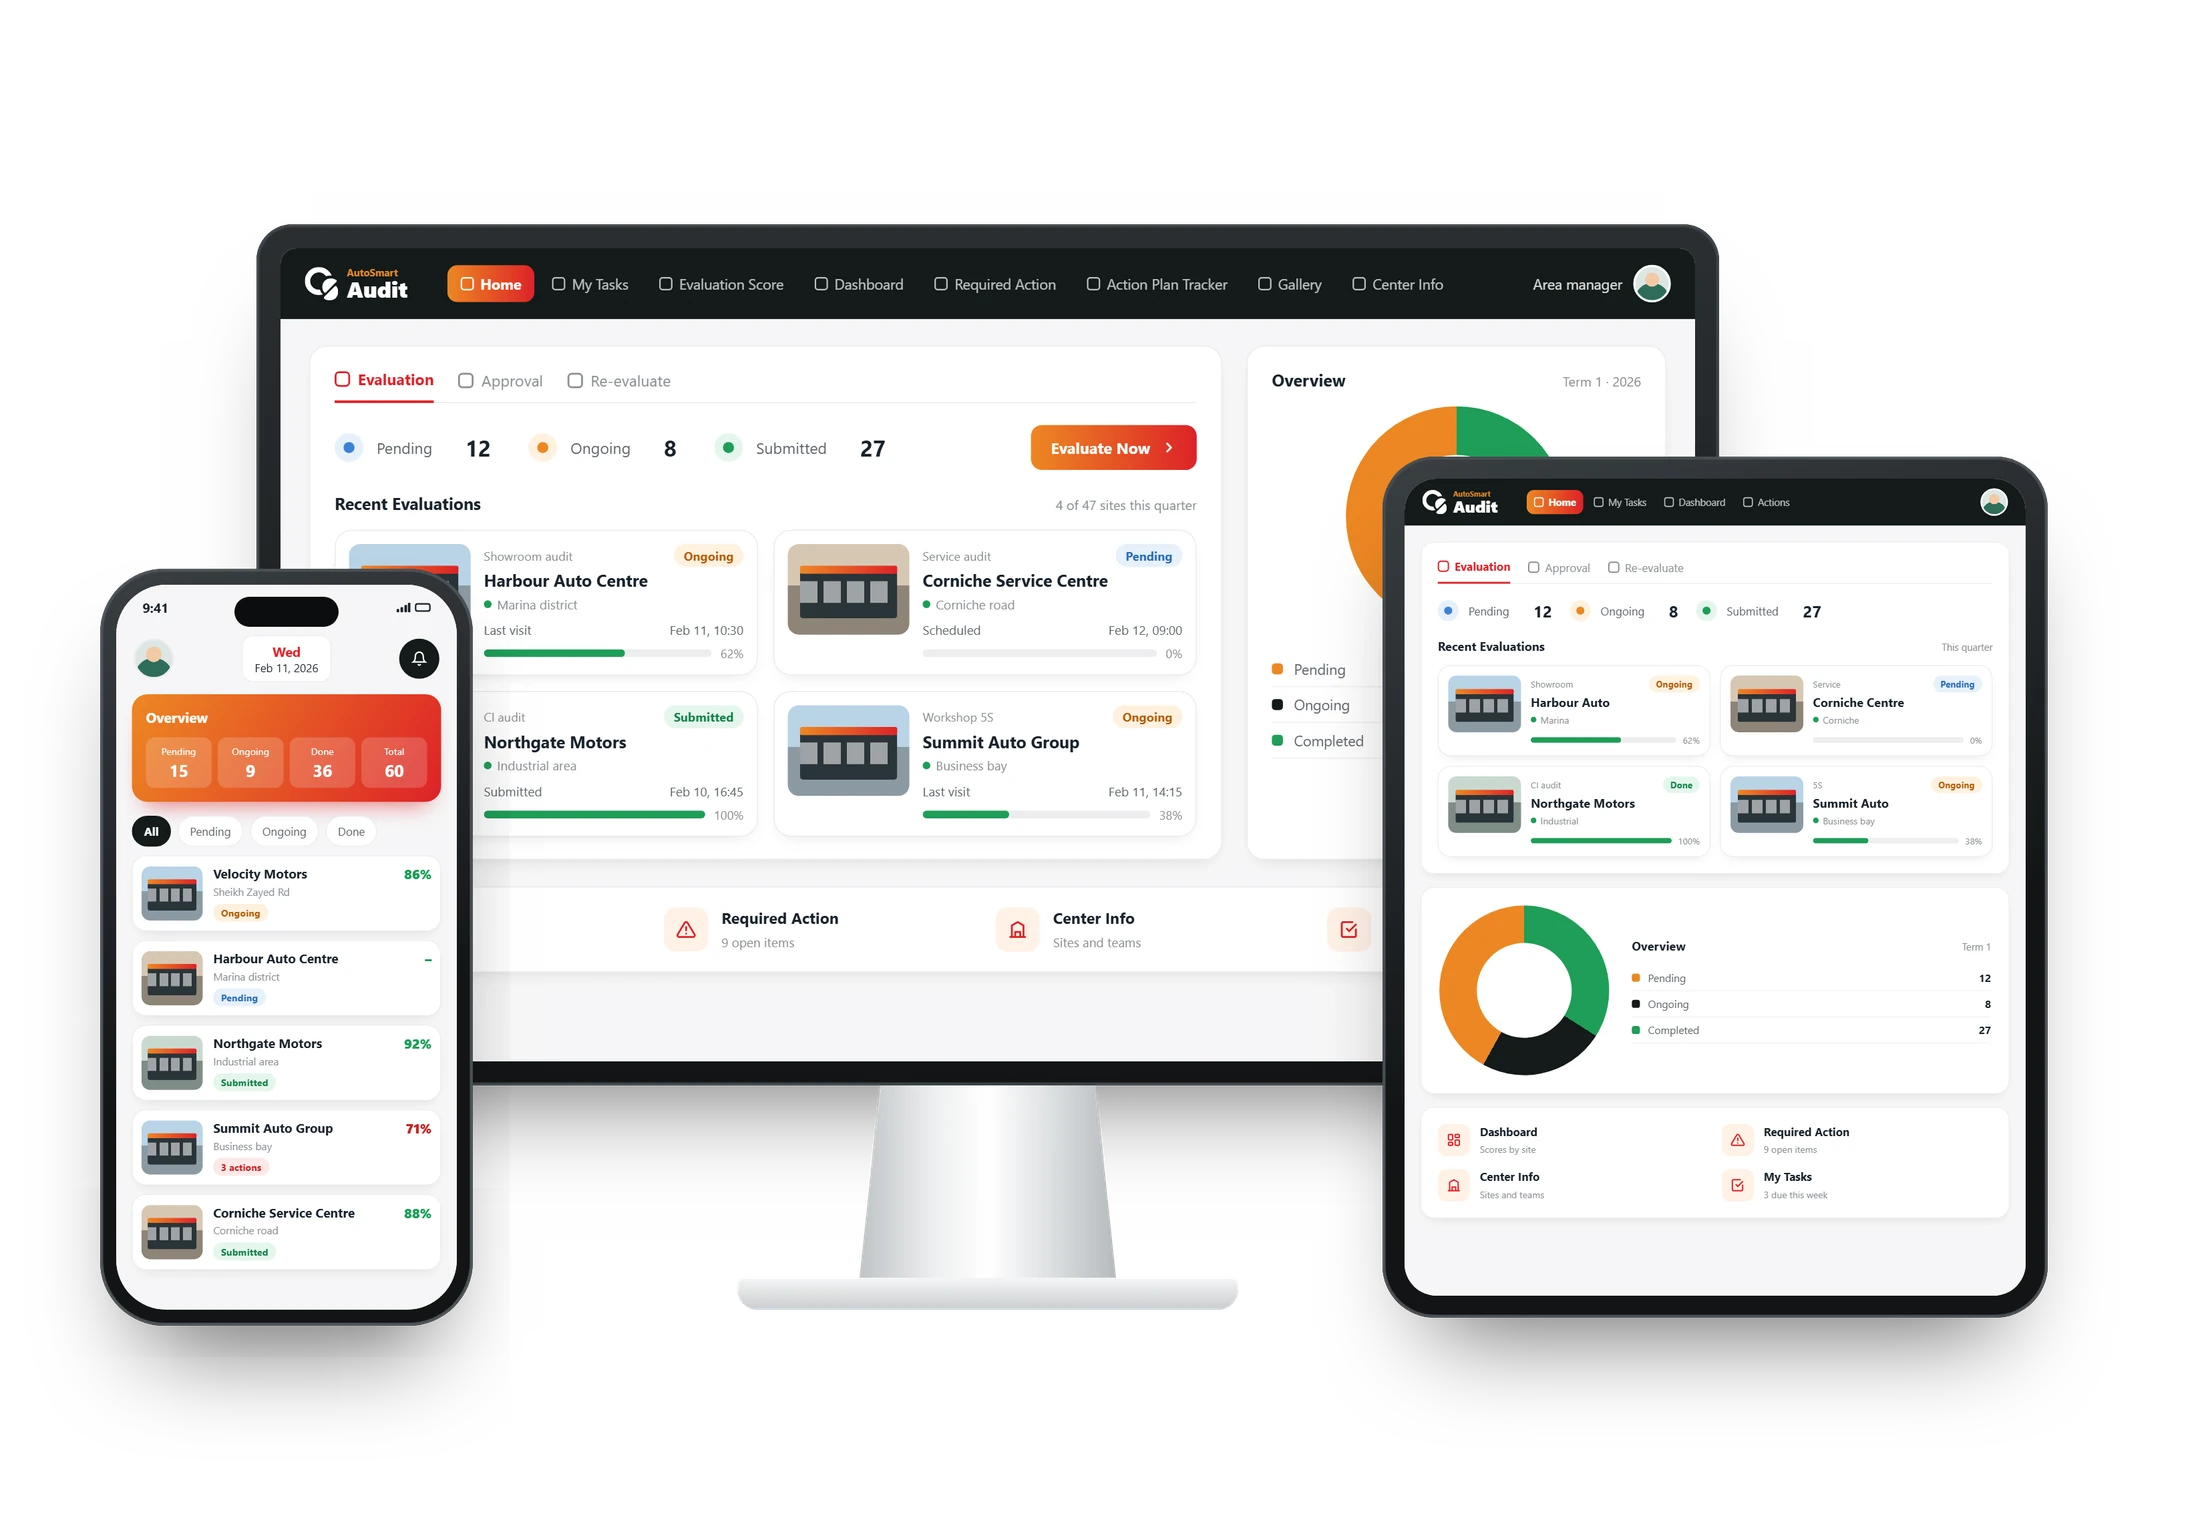
- Walk the site, standard by standard. Score each of the 11 checkpoints Pass, Fail or N/A. N/A only where the standard rules it out, with the reason recorded. Check 10 credit files for the information form, APR (RRSO) and signed receipt, 10 instalment ads, and 10 contracts with insurance or add-ons.
- Capture the evidence. A pass counts only with proof captured at the time of the audit: intermediary agreements, credit files, ad screenshots, contracts with add-ons and the CCD2 implementation plan.
- Give every fail an owner and a fix time. Record what you saw and who owns the fix. Each standard carries an ideal fix time, from immediate to 30 days, counted from audit submission (see the table above).
- Fix it, then prove it. The site fixes the cause and uploads proof of closure; the auditor checks the proof before closing the finding.
- Re-check at the next audit. Confirm closed findings stay closed, and look for the same fail at your other sites so one gap doesn't repeat across the network.
Who this guidebook is for
- Boards: the size of the risk
- F&I department: what to give the customer and when
- Auditors: credit files to check
A reference document, not legal advice. Fines and rules change: check the current text with the regulator or your legal adviser before acting.