What this guidebook covers
From 1 January 2027, companies that are not in the SII (Immediate Supply of Information) must invoice with Verifactu software. Using non-compliant software costs €50,000 per financial year. In VAT, applying the wrong scheme is fined up to 150% of the tax due, and above €120,000 of unpaid tax it is a tax crime with 1 to 5 years in prison.
This guidebook covers 6 tax standards for dealers, with 13 checkpoints: Verifactu or SII, complete invoices, the margin scheme for used goods (REBU), vehicle registration tax by CO2 band, intra-EU sales, and SII records sent on time. The guidebook PDF is in Spanish.
The 6 tax standards
| Code | Standard | Ideal fix time |
|---|---|---|
| FIS-01 | Verifactu or SII | 30 days |
| FIS-02 | Complete invoices | 7 days |
| FIS-03 | REBU applied correctly | 30 days |
| FIS-04 | Registration tax | 7 days |
| FIS-05 | Intra-EU sales | 7 days |
| FIS-06 | SII on time | 72 hours |
How to run a Spanish tax, Verifactu and VAT audit, step by step
- Confirm what applies. Confirm whether the company is in the SII (turnover above €6 million) or must use Verifactu from 2027. The Basque Country and Navarre have their own systems (TicketBAI).
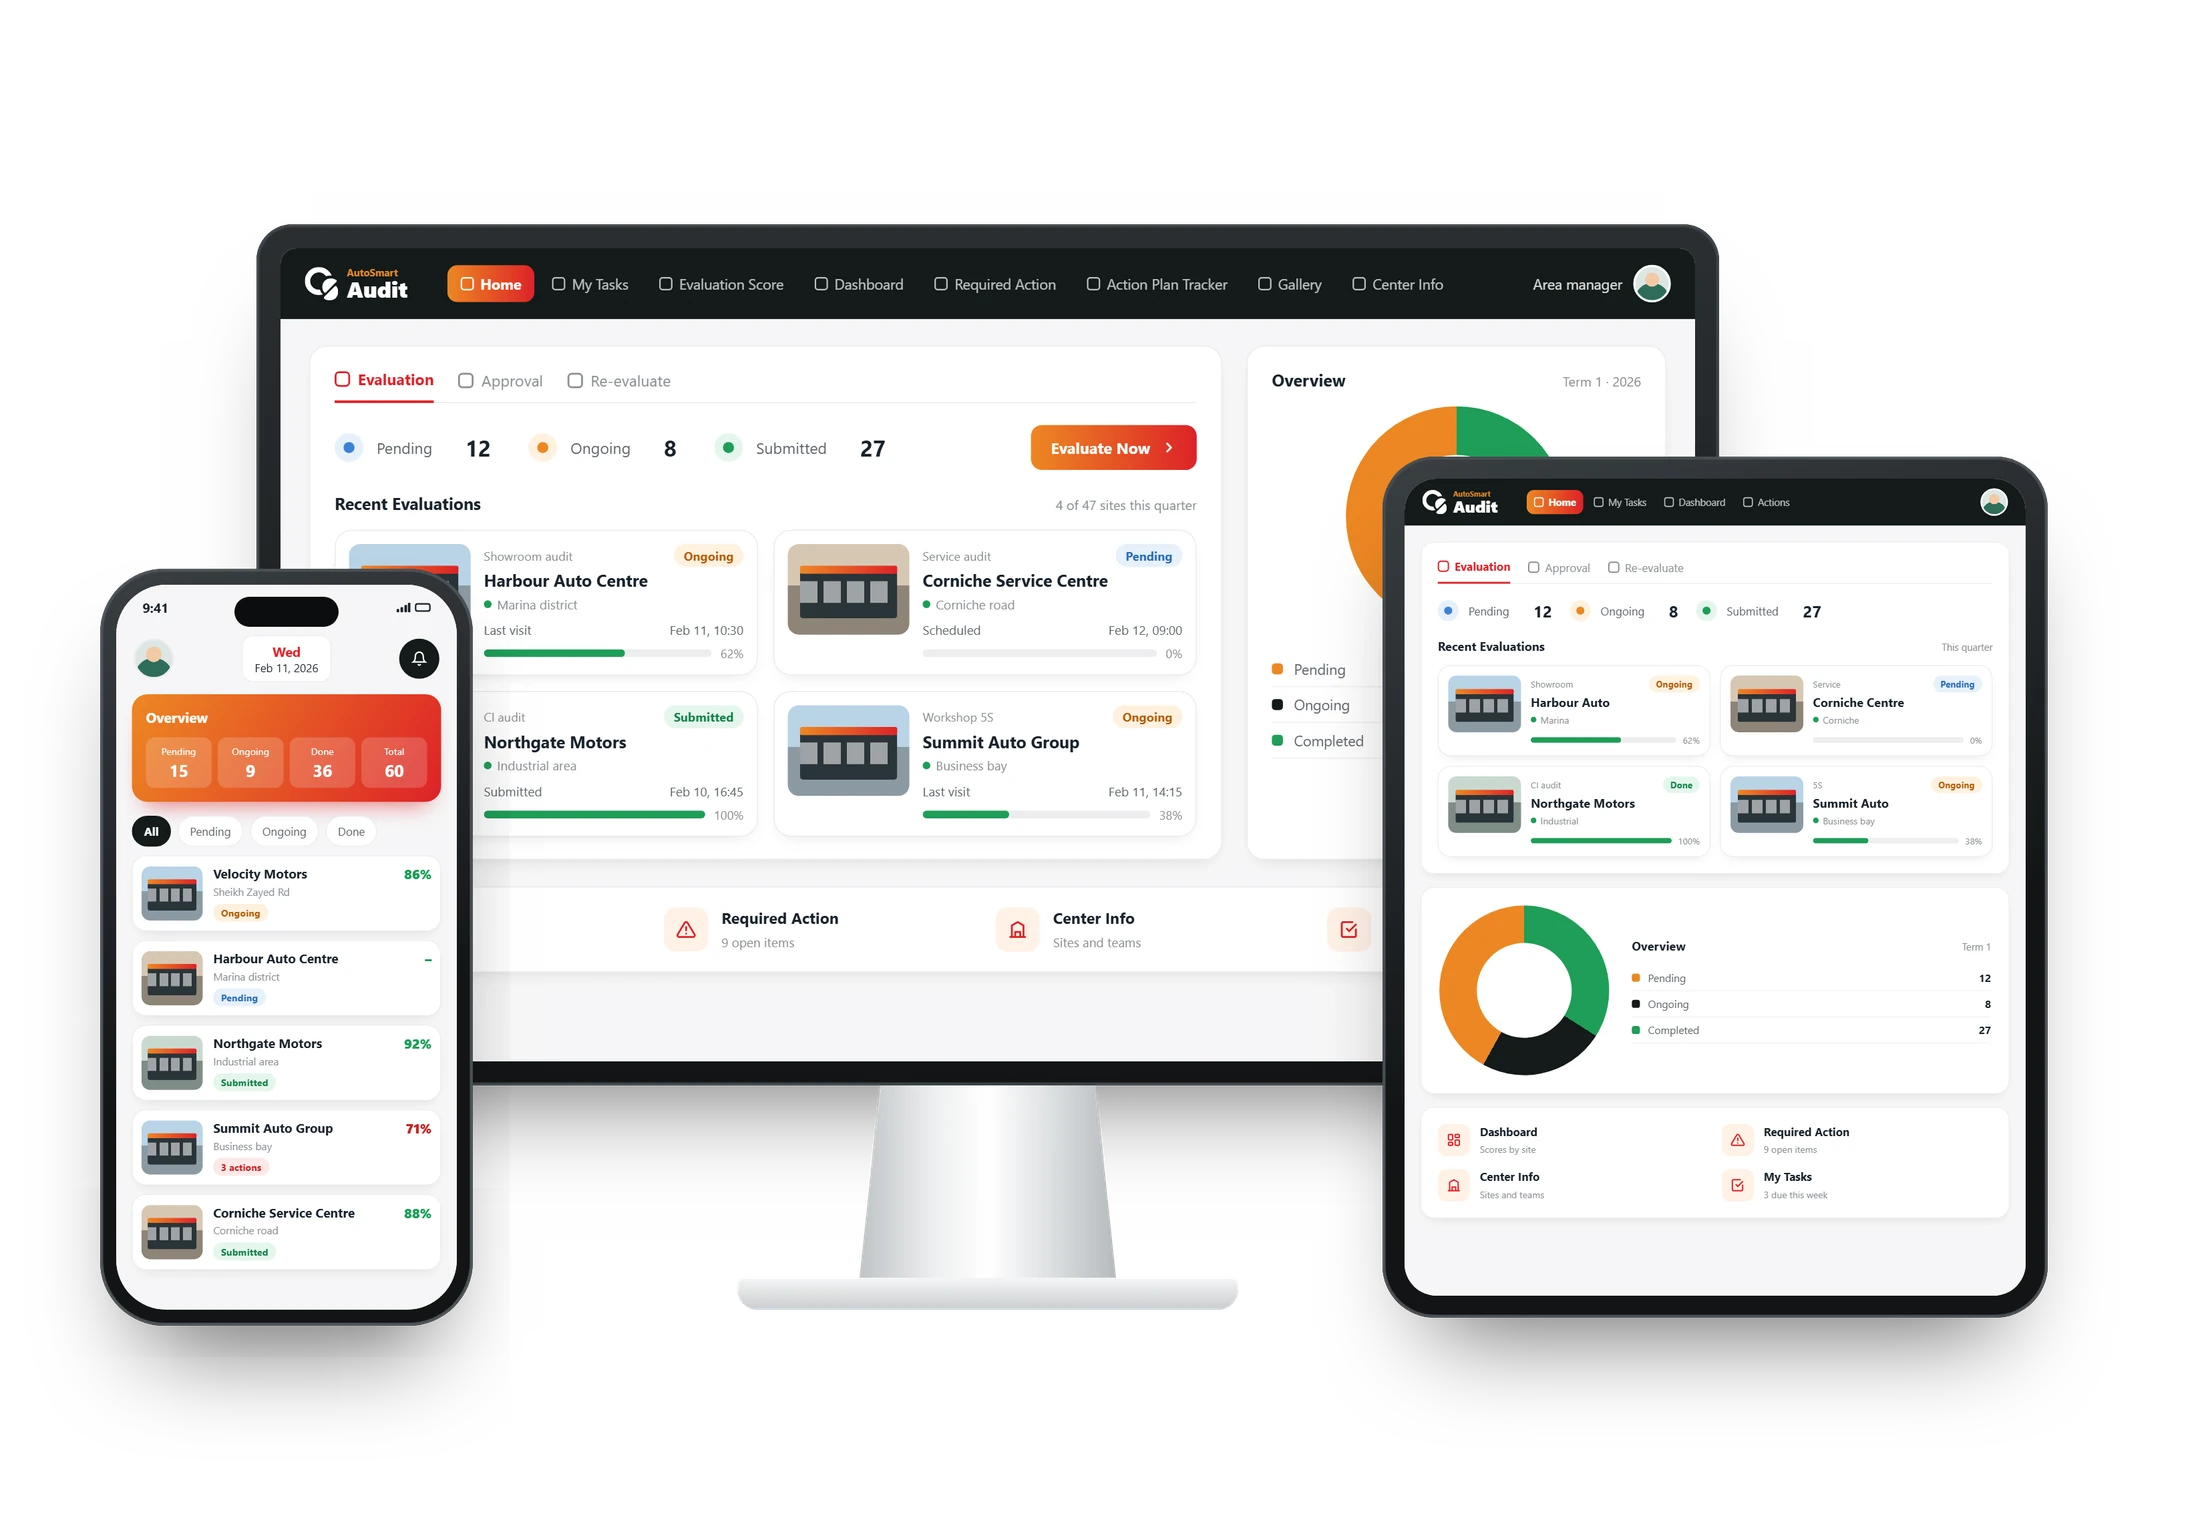
- Walk the site, standard by standard. Score each of the 13 checkpoints Pass, Fail or N/A. N/A only where the standard rules it out, with the reason recorded. Ask the DMS provider for the Verifactu certificate, then review 20 invoices, 10 REBU sales, 10 registration tax returns (form 576), 5 intra-EU sales and the SII dashboard.
- Capture the evidence. A pass counts only with proof captured at the time of the audit: the software provider's responsible declaration, invoices, purchase invoices for REBU cars, form 576 returns, VIES checks and CMR transport documents, and the SII report.
- Give every fail an owner and a fix time. Record what you saw and who owns the fix. Each standard carries an ideal fix time, from 72 hours to 30 days, counted from audit submission (see the table above).
- Fix it, then prove it. The site fixes the cause and uploads proof of closure; the auditor checks the proof before closing the finding.
- Re-check at the next audit. Confirm closed findings stay closed, and look for the same fail at your other sites so one gap doesn't repeat across the network.
Who this guidebook is for
- Finance directors: control systems and VAT schemes
- Administration: issues and records invoices
- Auditors: review invoices, REBU and tax returns
A reference document, not legal advice. Fines and rules change: check the current text with the regulator or your legal adviser before acting.